Yes, most long-term care insurance policies cover in-home care, and if you’re reading this, you probably already suspected that but need the specifics before you make a decision or file a claim. You’re not wrong to want a straight answer instead of another wall of insurance jargon.
Here’s the promise: by the end of this article, you’ll know what services get covered, what triggers your benefits, how the waiting period works, and what to do if your claim gets denied. So does long-term care insurance cover in-home care in every case? Not automatically. It depends on your policy, your diagnosis, and a few details most people skip over until it’s too late.
How Long-Term Care Insurance Covers In-Home Care
Long-term care insurance covers in-home care by paying a daily or monthly benefit toward services like personal care, homemaker help, and skilled nursing once you meet your policy’s eligibility requirements. Most modern policies treat home care as a covered setting right alongside assisted living and nursing homes. That wasn’t always true. Older policies written before the mid-1990s sometimes limited benefits to facility care only, so if you’re holding a policy from that era, check the wording closely.
Insurers pay benefits one of two ways: reimbursement or indemnity. Reimbursement policies pay you back for actual costs, up to your daily limit, after you submit receipts. Indemnity policies pay a flat amount once you qualify, no matter what you actually spend. Reimbursement is more common, and it’s the type most people mean when they ask about long-term care insurance home care reimbursement.
What Types of In-Home Care Services Are Typically Covered?
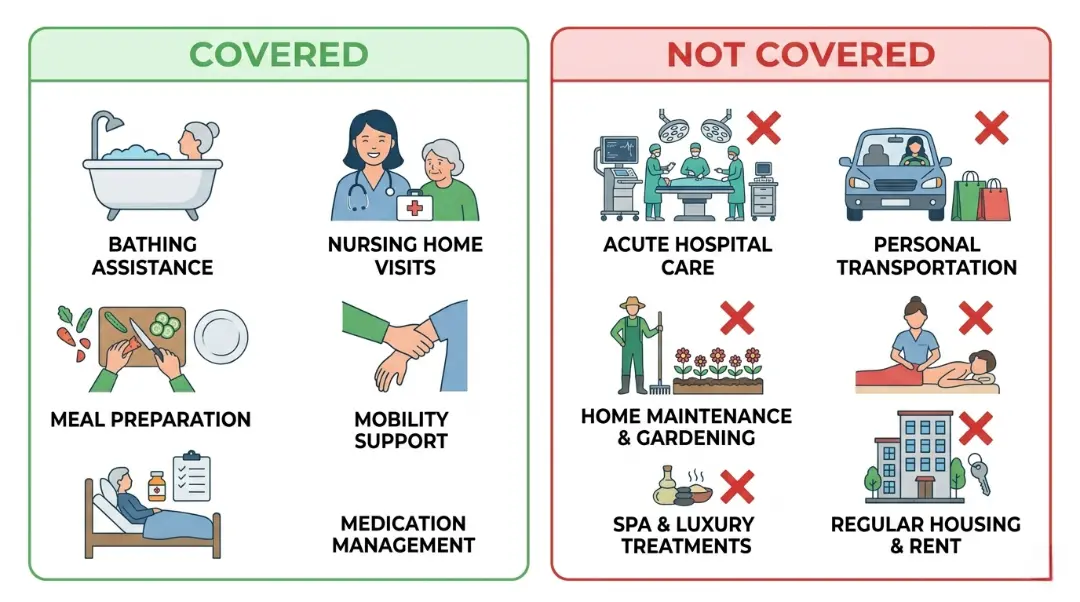
Long-term care insurance policies typically cover personal care assistance, companion care, homemaker tasks, skilled home health nursing, and adult day care services. The care plan must usually be prescribed by a licensed healthcare professional to qualify.
Covered in-home services generally include:
-
Personal Care: Assistance with bathing, grooming, dressing, toileting, and mobility.
-
Homemaker Services: Meal preparation, light housekeeping, laundry, and running essential errands.
-
Skilled Nursing: Wound care, medication administration, and physical therapy provided by a Registered Nurse (RN) or Licensed Practical Nurse (LPN).
-
Respite Care: Temporary professional care designed to give family caregivers a short break.
Standard home care covered by long term care insurance focuses on functional support rather than intensive medical treatments.
What Are the Eligibility Triggers for LTC Benefits?
Eligibility triggers for LTC benefits require a licensed physician to certify that you cannot perform at least two Activities of Daily Living (ADLs) or that you suffer from severe cognitive impairment like Alzheimer’s disease.
Insurers evaluate two main criteria to approve claims:
-
Activities of Daily Living (ADLs): Standard policies require assistance with two or more of the six core ADLs: bathing, dressing, eating, transferring (moving from bed to chair), toileting, and continence.
-
Cognitive Impairment: If a policyholder has dementia or Alzheimer’s, benefits kick in when supervision is necessary to protect their health and safety, even if they can perform physical ADLs.
A physician must submit a formal plan of care documenting these exact needs.
Understanding the Elimination Period (The Waiting Period Nobody Talks About)
The elimination period is a policy deductible measured in days rather than dollars, requiring you to pay for in-home care out of pocket for 30, 60, or 90 days before insurance payments begin.
How your policy counts these days significantly impacts your finances:
-
Calendar-Day Counting: The clock ticks every calendar day once your medical eligibility is certified, regardless of how many days you receive paid care.
-
Service-Day (Paid-Care) Counting: The clock advances only on days you pay a caregiver to enter your home. If you receive care three days a week, a 90-day elimination period takes 30 weeks to satisfy.
Knowing how to use ltc insurance to pay for in-home senior care requires planning for these initial out-of-pocket costs during the waiting window.
Can You Use Long-Term Care Insurance to Pay for a Home Health Aide?
Yes, LTC insurance can pay for a licensed home health aide as long as they work for a licensed home care service and the policy covers custodial care. Some policies have features of cash benefits that allow policyholders to recruit on their own without agency limitations.
If your insurance requires an agency, contact the insurer first and check that the agency you choose is an approved provider. Home care organizations that accept LTC insurance will usually do most of the claims paperwork for you, which relieves a lot of load off the family.
an a Family Member Be Paid as a Caregiver Under LTC Insurance?
A family member can be paid as a caregiver under some long-term care insurance policies, but it depends entirely on your specific plan, since many traditional policies exclude spouses and close relatives from paid caregiver benefits. Cash or indemnity-style policies are far more flexible here because they pay a set amount regardless of who provides the care.
Reimbursement policies are stricter. Many require the caregiver to be licensed, trained, or affiliated with a home care agency, which rules out an adult child providing informal help. Some policies make an exception for family members who complete a caregiver training course or get hired through a licensed agency as a formal employee.
Step-by-Step: How to File a Claim for In-Home Care
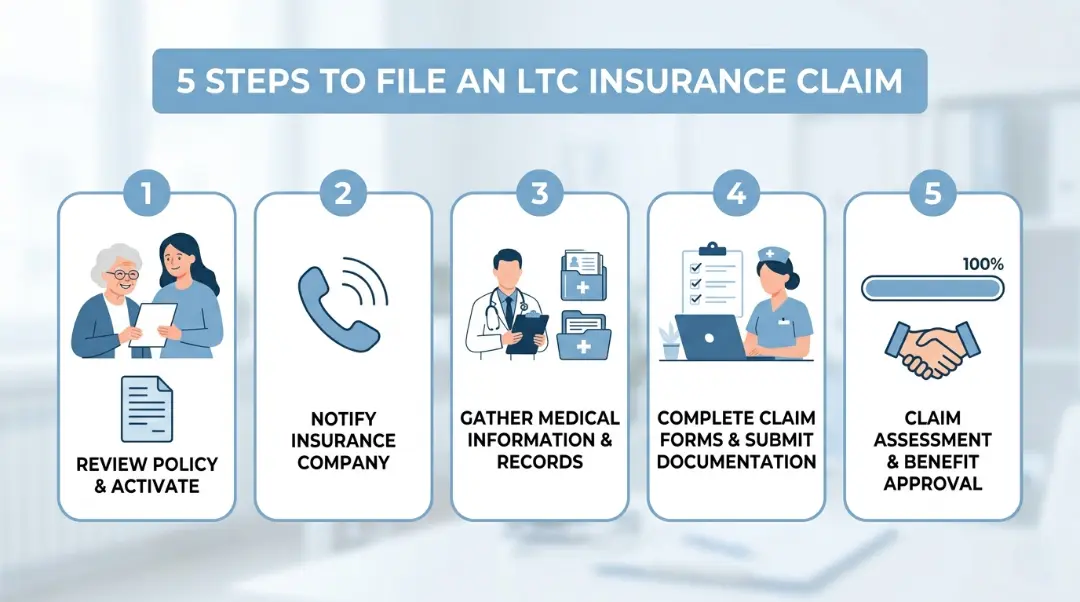
Filing an in-home care claim involves notifying your insurer, submitting medical documentation from a physician, completing an assessment, establishing a plan of care, and submitting weekly itemized care invoices.
Common Myths About Long-Term Care Insurance
Myth 1: Medicare covers in-home personal care. Medicare covers skilled home health services, like nursing visits and therapy, but it does not cover custodial care (bathing, dressing, eating). The hours are also limited, and you can’t choose your agency.
Myth 2: LTC insurance covers everything. It covers what the policy says it covers, up to the benefit limit. Supplemental benefits like home modifications or durable medical equipment may be included, but they come with their own rules.
Myth 3: Premiums are your only cost. The elimination period means you’ll pay out-of-pocket before benefits begin. Factor this into your planning.
What to Do If Your Claim Is Denied
Denials happen, often for small reasons. A care plan might list assistance with two ADLs, but if the caregiver’s invoice only documents one, that day’s claim gets rejected.
Here’s how to respond:
- Request a written explanation from the insurer. They’re legally required to provide one.
- Gather complete documentation from the home care provider, including detailed service logs.
- File a formal appeal within the deadline stated in the denial letter.
- Contact your state’s Department of Insurance if the denial seems unfair or is taking too long.
- Consult an elder law attorney for complex denials, especially those involving cognitive impairment.
Alternatives When LTC Insurance Doesn’t Cover Everything
- Medicaid waiver programs can cover custodial in-home care for qualifying low-income individuals
- VA benefits for veterans can supplement or replace LTC insurance entirely
- LTC insurance tax deductions premiums are often partially deductible; consult a tax advisor
- Inflation protection riders on newer policies help benefit amounts keep up with rising care costs
Finding Trusted Home Care Near You
If you’re looking for home care services in Denver or the surrounding area, Castle Pines Home Care offers licensed, compassionate in-home care that works directly with LTC insurance policies. Our team handles the paperwork, coordinates with insurers, and makes sure your loved one gets the care they’ve earned.
Contact us today to learn how we can help your family navigate LTC insurance and get care started quickly.
Frequently Asked Questions
Does long-term care insurance cover in-home care for dementia patients?
Yes. Severe cognitive impairment, including Alzheimer’s and dementia, is a standard eligibility trigger in most LTC policies. Clinical documentation and a home nurse assessment are typically required.
What is the elimination period in LTC insurance?
It’s a waiting period, usually 30–90 days, during which you pay out of pocket before benefits begin. Most policies backdate payments to the start of care.
Can LTC insurance pay a family member caregiver?
Cash benefit policies typically allow this. Reimbursement policies usually require invoices from a licensed agency.
Does private insurance cover home health care?
Some private health insurance plans cover skilled home health care after a hospitalization, but they rarely cover long-term custodial care. LTC insurance is specifically designed for that purpose.
What home care benefits does Medicare typically not cover?
Medicare does not cover ongoing personal care, such as bathing, dressing, or companion care. It only covers short-term skilled care tied to a medical condition.