Medical expenses add up fast when you or a family member needs daily support at home. Facing rising costs, you’re likely wondering if medical relief extends to these services. The short answer is yes, home health care is tax deductible under specific Internal Revenue Service rules.
You can reduce your taxable income if your care expenses meet strict IRS guidelines, such as passing the 7.5% Adjusted Gross Income threshold. In this guide, we’ll walk through exactly what qualifies, how to calculate your savings, and how to file your return correctly.
When Is In-Home Care Tax Deductible?
In-home care is tax deductible when the services are medically necessary, prescribed by a doctor as part of a formal care plan, and the total unreimbursed medical expenses exceed 7.5% of your adjusted gross income (AGI). The care also can’t be reimbursed by Medicare, Medicaid, or private insurance.
The IRS lays out these rules clearly in Publication 502. Three conditions must all be true at the same time:
- The care is part of a physician’s documented care plan
- Your total qualifying medical expenses go above 7.5% of your AGI
- None of those expenses were paid back by insurance or government programs
If all three boxes are checked, you have a real deduction on the table.
There’s also an important exception for people with chronic illness. If a licensed health care practitioner certifies that someone has severe cognitive impairment or has lost the ability to perform at least two activities of daily living (ADLs) for 90 days or more, then even personal and household care becomes tax deductible. This is a key rule that many families miss entirely.
Home Care and Home Health Care Expenses That Are Tax Deductible
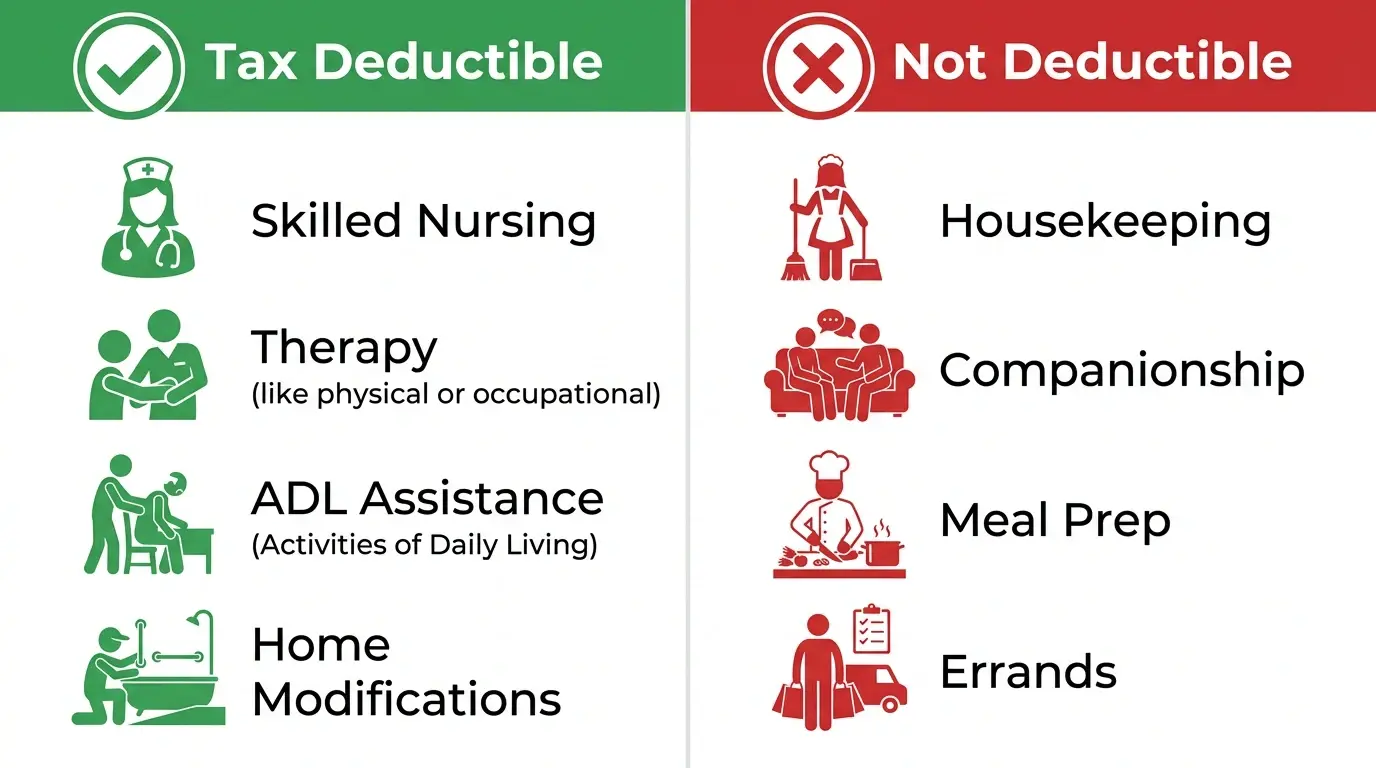
A short list of what typically qualifies, based on IRS Publication 502:
- Nursing services, including medication management and wound care
- Personal care assistance (bathing, dressing, toileting) tied to a documented medical need
- Physical, occupational, or speech therapy delivered at home
- Home health aide services provided under a licensed practitioner’s care plan
- Transportation to and from medical appointments
- Certain home modifications, like grab bars or wheelchair ramps, when prescribed for a medical condition
- Long-term care insurance premiums, up to age-based IRS limits
Notice that the common thread is medical necessity. A home health aide who helps a stroke patient relearn daily routines fits the bill. A general housekeeper doesn’t, even if the same person happens to need both.
Home Care Services That Aren’t Tax Deductible
Home care services aren’t tax deductible if they consist purely of personal, companion, or household support without a physician’s medical plan. Expenses for general house cleaning, meal prep, laundry, and errands do not qualify as medical deductions under standard IRS tax codes.
The IRS strictly separates medical care from general household maintenance. If a healthy individual hires someone simply for convenience, those costs are non-deductible personal expenses.
Common Non-Deductible Line Items
-
General Housekeeping: Maid services, dusting, vacuuming, and general household chores.
-
Companion Care: Social visits, conversation, or accompanying someone to social outings without personal care assistance.
-
Meal Preparation: Standard grocery shopping and cooking services, unless specifically tailored under a prescription.
-
Care Provided by Family Members: Payments made to a spouse or dependent family member for caregiving services cannot be claimed as a tax deduction.
If a home care worker splits their shift between personal care (like assistance with bathing) and general housework, you must divide the bill. Only the percentage of time spent directly on qualified personal care or medical assistance counts toward your medical expense deduction.
Who Can Deduct Home Care Expenses on Their Taxes?
Care recipients, spouses, and adult children who claim the care recipient as a dependent can deduct home care expenses on their taxes. The person paying the bills must provide more than half of the individual’s total financial support during the tax year to claim the deduction.
Determining who legally claims the deduction depends on family structure and financial contributions.
Self-Filing Seniors and Individuals
If you pay out-of-pocket for your own in-home support, you report the qualified costs directly on your personal tax return. The same rule applies if you pay for care received by your spouse.
Family Caregivers and Adult Children
Many adult children manage financial care for aging parents. To claim your parent’s medical expenses on your return:
-
They must qualify as your dependent under IRS rules, or
-
They would qualify as your dependent except they earned over the gross income limit, but you still provided more than 50% of their total support during the calendar year.
If multiple siblings jointly support a parent, you can use a Multiple Support Agreement (IRS Form 2120) to assign the deduction to one primary caregiver who contributes at least 10% of the total support.
Understanding Home Care Tax Deductions
To benefit from medical expense deductions, your total qualifying healthcare costs must exceed a specific portion of your income. The IRS sets this threshold at 7.5% of your Adjusted Gross Income (AGI).
You can only deduct the amount that surpasses this 7.5% limit.
A Practical Calculation Example
Let’s look at how the math works in practice:
-
Adjusted Gross Income (AGI): $60,000
-
7.5% Threshold: $4,500 ($60,000 x 0.075)
-
Total Qualified Medical & Home Care Expenses: $12,000
-
Deductible Amount: $7,500 ($12,000 – $4,500)
In this scenario, you reduce your taxable income by $7,500 on Schedule A.
| Financial Parameter | Amount |
| Adjusted Gross Income (AGI) | $60,000 |
| IRS 7.5% Floor | $4,500 |
| Total Out-of-Pocket Medical Costs | $12,000 |
| Final Tax Deduction | $7,500 |
How to Claim Home Care Deductions
To claim home care deductions, you must file Schedule A with your federal tax return and list your qualifying medical expenses under the Medical and Dental Expenses section. You cannot claim this deduction if you take the standard deduction.
Here’s what you need to have on hand when filing:
- Invoices and receipts for all care services
- A written care plan from a licensed physician or health care practitioner
- A chronic illness certification (if applicable)
- Daily activity logs from caregivers showing time spent on medical vs. non-medical tasks
- Records of any reimbursements from Medicare, Medicaid, or insurance
If you hired an in-home caregiver directly as a household employee, IRS Publication 926 may allow you to deduct certain employer taxes you paid on their behalf, such as Social Security tax and state employment taxes. This doesn’t apply if you hired through an agency since the caregiver is legally the agency’s employee in that case.
What If You Don’t Itemize?
If the standard deduction makes more financial sense for you, you still have options. Beyond the FSA/HSA route mentioned above, check whether your state offers its own medical deduction. Several states have lower AGI thresholds or separate rules that can work in your favor even when the federal itemized deduction doesn’t.
How to Calculate Your Home Health Care Tax Deduction
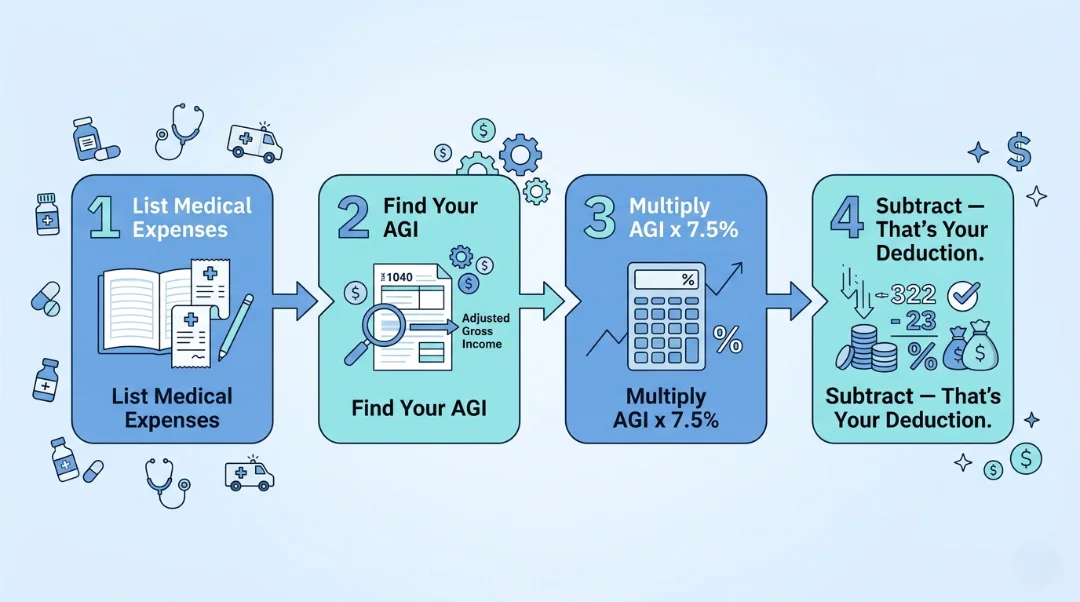
Calculating your deduction requires aggregating all family medical expenses for the calendar year, not just in-home care costs.
Combined Medical Expenses List
Include the following payments alongside home care to reach the 7.5% threshold faster:
-
Health insurance premiums (paid with post-tax dollars)
-
Prescription drugs and insulin
-
Out-of-pocket doctor, dental, and vision visits
-
Co-pays, deductibles, and hospital fees
-
Transportation costs for medical care (standard mileage rates or public transit fares)
-
In-home respite care for seniors provided by a home health aide
Step-by-Step Math Worksheet
-
Calculate your AGI (found on Form 1040, line 11).
-
Multiply your AGI by 0.075 to find your floor.
-
Sum all qualified out-of-pocket medical expenses incurred during the tax year.
-
Subtract step 2 from step 3.
The remaining positive number is your total allowable deduction.
Tax Deduction vs. Tax Credit: What’s the Difference?
Tax deductions reduce your overall taxable income based on your tax bracket, whereas tax credits provide a direct dollar-for-dollar reduction of your total tax bill. Tax credits generally deliver greater overall savings, but each option carries distinct IRS eligibility criteria.
Understanding how these two mechanisms differ helps you pick the right filing strategy.
Tax Deductions
A deduction lowers the portion of your income subject to federal tax. For instance, if you fall into the 22% tax bracket, a $1,000 deduction saves you $220 in cash. Medical expenses claimed on Schedule A act as deductions.
Tax Credits
A credit directly wipes out tax debt dollar for dollar. A $1,000 tax credit cuts your final tax bill by $1,000.
Dependent Care Tax Credit
Family caregivers should examine the Child and Dependent Care Credit (Form 2441). If you pay a professional caregiver or home care agency to care for a dependent while you work or look for work, you may qualify for this credit.
Final Thoughts
Figuring out is home health care tax deductible isn’t always a simple yes or no. It depends on what type of care is being provided, who’s paying for it, and how the numbers stack up against your income. The good news is that between the medical expense deduction, FSA/HSA options, and potential state-level rules, there are real opportunities to reduce what you owe.
If your loved one is dealing with dementia-related behavioral changes alongside their care needs, our article on What Stage of Dementia Is Anger? may also be a helpful read as you plan their care.
At Castle Pines Home Care, we work with families every day who are navigating both the emotional and financial sides of in-home care. If you’re looking for home care services in Denver and want to understand your options, we’re here to help. Contact us today to talk through what care might look like for your family.
Frequently Asked Questions
Is paying a family member for home care tax deductible?
Yes, in some cases. You can deduct payments made to a family member caregiver as long as they are not your spouse or your own dependent. Those payments must follow payroll tax rules and be reported as income by the caregiver.
Can I deduct home care for a parent who doesn’t live with me?
Yes. You can claim a parent as a dependent even if they live elsewhere, as long as you provide more than half of their annual support and they meet the IRS income and citizenship requirements.
Is home health care the same as long-term care for tax purposes?
Not exactly. Home health care refers to medically necessary services provided at home. Long-term care is a broader category that can include custodial care for chronically ill individuals. Both can be deductible under certain conditions, but the qualifying criteria differ slightly.
Does Medicare or Medicaid affect my deduction?
Yes. Any expenses reimbursed by Medicare, Medicaid, or private insurance cannot be deducted. Only unreimbursed out-of-pocket costs count toward your medical expense deduction.
Can I use an FSA or HSA for home health care costs?
Yes. Qualifying medically necessary home health care expenses, including skilled nursing, prescribed therapy, and medical equipment, can typically be paid with FSA or HSA funds, giving you a tax advantage without needing to itemize.
Are health care premiums tax deductible?
In many cases, yes. If you pay out-of-pocket health insurance premiums that aren’t subsidized by an employer or government program, they can be included in your total medical expense deduction on Schedule A. Self-employed individuals may deduct 100% of premiums without itemizing.